The mortgage industry is notoriously cyclical. When rates drop, loan officers are flooded with applications, working 16-hour days just to keep their heads above water. When rates rise, the focus intensely shifts to proactive lead generation and relationship building with real estate agents.
In both environments, the defining factor between average loan officers and top producers is operational leverage. You cannot double your origination volume if you are personally collecting W-2s, updating Encompass, and calling title companies for status updates.
Enter the Mortgage Virtual Assistant (VA). By integrating a dedicated, offshore professional into your origination team, you can drastically reduce your cost-per-loan while significantly increasing your capacity. In this guide, we break down exactly how elite mortgage professionals are utilizing VAs to dominate their local markets.
1. The Loan Officer’s Dilemma
A Loan Officer’s (LO) primary job is to generate business and structure loans. However, the regulatory environment and complexity of modern underwriting mean that a single loan requires dozens of micro-tasks.
When an LO tries to be a rainmaker, a processor, and a loan officer assistant (LOA) all at once, the pipeline inevitably clogs.
Symptoms of a Clogged Pipeline:
- You lose deals because you didn’t reply to a Realtor fast enough.
- Loans are delayed because a simple document request was forgotten.
- You stop making proactive outbound sales calls because you are “too busy” putting out fires.
A Mortgage VA cures these symptoms by taking over the backend, allowing the LO to remain front-facing.
2. Pre-Approval and Intake Support
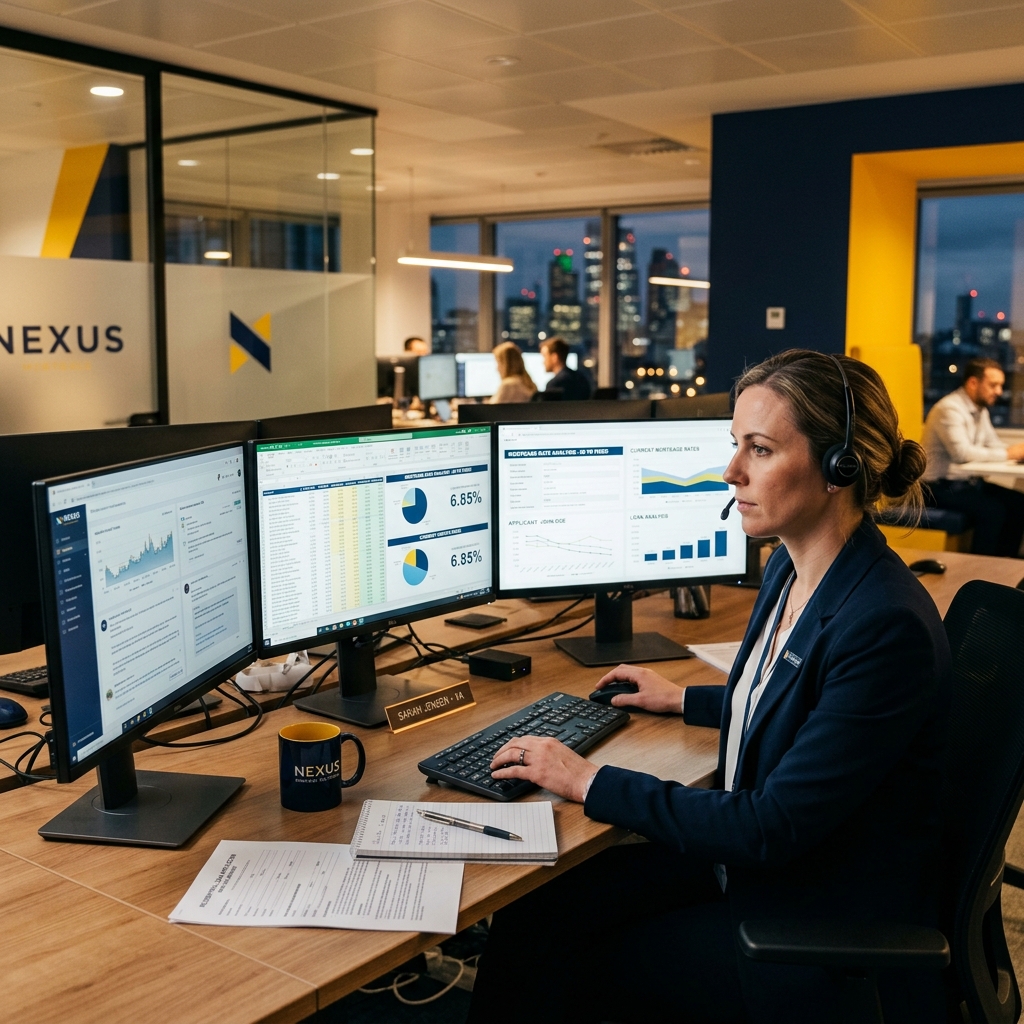
The initial stages of a loan are data-heavy and repetitive. A Mortgage VA can act as your intake specialist, ensuring that every file is perfectly prepped before you even look at it.
The VA Intake Workflow:
- Application Review: The VA monitors incoming 1003 applications for completeness.
- Document Collection: They send out initial needs lists (W-2s, pay stubs, bank statements) and follow up relentlessly until the borrower provides them.
- CRM Data Entry: They input the borrower’s data into your CRM (like Salesforce or HubSpot) and your Loan Origination System (LOS) like Encompass, Calyx, or Arive.
- Credit Pulls: (If authorized) The VA can initiate soft or hard credit pulls and highlight potential red flags for your review.
By the time the file reaches your desk, it is fully populated and ready for you to structure the loan and issue the pre-approval letter.
3. Seamless Loan Processing Assistance
While a VA may not replace a licensed, onshore Loan Processor for complex underwriting conditioning, they are the ultimate force-multiplier for your existing processing team.
By having a VA act as a “Processor’s Assistant,” you can increase the capacity of your expensive onshore staff.
| Task Category | VA Responsibility | Processor Responsibility |
|---|---|---|
| Third-Party Orders | Ordering title, appraisals, HOI, and VOEs. | Reviewing the returned documents for accuracy. |
| Condition Chasing | Calling borrowers to remind them to sign disclosures. | Clearing conditions with the underwriter. |
| File Scrubbing | Naming and organizing PDFs into the correct LOS folders. | Submitting the clean file to underwriting. |
This division of labor ensures that high-level staff are only doing high-level work, drastically reducing the time it takes to move a loan from “Clear to Close”.
4. Realtor and Client Communication Management
One of the biggest complaints borrowers and real estate agents have about loan officers is a lack of communication. In a fast-paced market, silence causes anxiety.
Your Mortgage VA can manage proactive communication. They can send out automated, yet personalized, milestone updates every Tuesday and Friday.
- “Hi John, just letting you know the appraisal was ordered today!”
- “Hi Sarah, your file is officially out of underwriting, we are just waiting on the final title policy.”
This proactive approach prevents the LO from receiving dozens of inbound “What’s the status?” phone calls, freeing up hours of time each week while simultaneously improving client satisfaction scores.
5. Marketing and Database Reactivation
Past clients are a goldmine for future refinances and referrals, yet most LOs completely ignore their database once the loan funds.
A Mortgage VA can manage your entire post-close marketing strategy:
- Annual Mortgage Reviews: The VA tracks past closing dates and automatically schedules Annual Mortgage Reviews (AMRs) on your calendar.
- Rate Monitoring: If rates drop, the VA can cross-reference your database to identify clients who would benefit from a refinance, teeing them up for you to call.
- Social Media: Posting educational content about down payment assistance, rate trends, and loan products on your LinkedIn and Facebook pages.
6. The Economics of the Mortgage VA
In a margin-compressed environment, controlling costs is just as important as generating revenue. Traditional, onshore LOAs demand high salaries, bonuses, and benefits.
By utilizing a MaverickAssist Mortgage VA, you convert a massive fixed cost into a highly affordable, scalable solution.
The ROI is simple: If a VA saves you just 3 hours a day, that is 15 hours a week of recovered time. If you use those 15 hours to make outbound sales calls and build relationships with real estate agents, you only need to close one extra loan per month to completely pay for the VA’s entire yearly cost. In reality, most LOs see a 30-50% increase in volume within the first 6 months of properly integrating a VA.
Don’t let admin work cap your income. Scale your origination business with a dedicated Mortgage VA today.